Struggling with money management? You’re not alone. Many find the financial world overwhelming.
Creating a full financial plan might sound daunting, but it’s your roadmap to financial security. Let’s be honest (handling) finances is tricky. You’ve got savings, investments, debts, and more.
How do you balance it all? With the right approach, you can transform chaos into clarity.
I’ve been there, navigating the maze of financial strategies. What makes this different? We dive into core finance strategies, explore market momentum, and even touch on high-yield wealth models.
It’s not just about numbers; it’s about making informed decisions that align with your goals.
Why trust this guide? Because we’ve consulted with experts who live and breathe finance. You’ll get takeaways shaped by real-world experience, not just theory.
Ready to take control? This article will provide you with actionable steps to craft a plan that works for you. Let’s get started.
Step 1: Budgeting Reimagined
Budgeting is more than just slashing expenses. It’s about optimizing cash flow to find where your money’s hiding. Ever wonder why your wallet’s always empty at month’s end?
It’s not magic (it’s) math. Let’s break it down. Start with a simple cash flow analysis: Income minus fixed costs minus variable costs equals your investable capital.
This isn’t rocket science, but it does require some honesty. What’s really eating your cash?
We all have financial leaks (those) sneaky expenses that add up over time. Think about subscription services you forgot existed or those impulse buys (you know the ones). Redirect that money toward your growth goals instead.
Imagine the potential when you stop hemorrhaging cash and start channeling it into something meaningful.
Knowing your cash flow is like holding the map to your financial future. It’s the foundation for everything else.
Without understanding where your money goes, a full financial plan is just a pipe dream. This first step is non-negotiable. You can’t build a plan on guesswork.
Oh, and here’s a pro tip: check out how understanding tax benefits financial planning can boost your plan over at understanding tax benefits financial planning. Trust me, every dollar counts when you’re trying to maximize your returns. Remember, clarity now saves chaos later.
So, are you ready to take control of your money?
Your Financial North Star: Precision Goals
Vague goals like “save for retirement” are a waste of time. Let’s cut to the chase. You need specific goals.
A full financial plan demands it. Think about it. What are you saving for?
A beach house? Kid’s college? You can’t just wing it.
You’ve got to be SMART: Specific, Measurable, Achievable, Relevant, Time-bound.
Here’s a system for you:
| Goal | Target Amount ($) | Target Date (Years) | Required Monthly Investment ($) |
|---|
Pro tip: Break down your goals. Short-term (1-3 years), mid-term (4-10 years), and long-term (10+ years) each need their own plan. It’s like playing chess: every move counts.
Short-term might mean safer investments, while long-term lets you take bigger risks. These goals are your “why.” They’re the fire that keeps you going.
Without them, your plan’s just a bunch of numbers. You know what I mean? This is what makes your plan stick.
It’s your roadmap, your GPS for financial success. So, what’s your next move?
Building Your Core Investment Portfolio: The Essentials
Creating a full financial plan starts with a solid investment portfolio. You know, like building a house on a strong foundation. But where do you start?
Asset allocation is your first step. It means spreading your money across different asset classes to manage risk. Think of it like a balanced meal.
You wouldn’t eat only carbs, right? You need proteins and veggies too. In investing, that means mixing stocks, bonds, and alternatives.
Stocks, or equities, are like the meat of your portfolio. They offer growth but come with higher risk. Bonds are the potatoes.
Stable but less exciting. Alternatives like real estate and commodities are the side dishes. They add flavor and diversity.
Each has its own role, and together they form a complete meal. Err, portfolio.
Risk tolerance is key. How do you handle uncertainty? If your investments lost 20%, would you panic?
If not, you might be more aggressive. But if you break into a cold sweat, maybe stick to safer bets. Here’s a quick self-assessment: What’s your reaction to market swings?
How long can you wait for returns? Think about it.
The relationship between risk and return is simple. Higher risk can lead to higher rewards. It’s like gambling, but with more plan.
Over time, a well-diversified portfolio can yield solid returns. But remember, it’s a long game. For more takeaways on balancing risk, check out Risk Management In Finance Techniques.
Understanding these basics sets you on the path to financial health.
Step 4: Riding the Waves of Market Momentum
Want to turbocharge your wealth? Let’s cut to the chase. Leveraging market momentum is like catching a wave (assets) that have been performing well tend to keep it up.
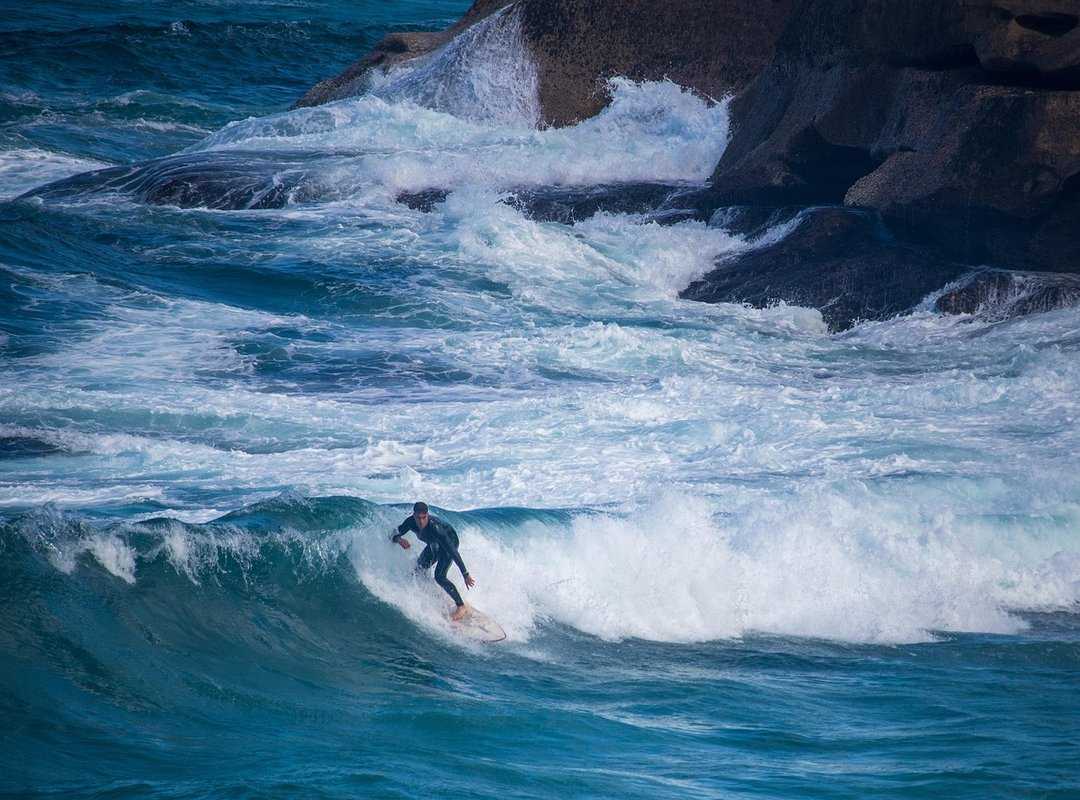
It’s the thrill you’d expect but with a calculated twist. This isn’t just about sitting back and letting things happen. It’s active.
Strategic. We need to be smart, not reckless.
So what’s the play here? High-yield models. You’re probably wondering if this is just another buzzword.
Nope. It means allocating a small, defined percentage of your portfolio to those higher-risk, higher-potential-reward investments. Why?
Because every financial plan deserves a shot at greatness, and that’s where calculated risks come in.
A full financial plan should not be left to chance. You can learn more about it what is a full financial plan. But here’s the kicker: it’s not about gambling.
It’s about research, understanding, and knowing when to hold ’em and when to fold ’em. And yes, that’s straight from the song.
It’s key to stick to the “small, defined percentage” rule. We’re protecting the core. No need to throw the entire house on the line.
The thrill of high-yield models is real, but we want to come out on top, not lose our shirt.
Does this sound like a lot to juggle? It is. But then again, if it was easy, everyone would be doing it.
So, are you ready to ride the wave or just drift?
Step 5: Master the Feedback Loop
A full financial plan isn’t just something you set and forget. It’s alive. I always say it’s much like a pet.
It needs regular attention. But how often should you check in? Every quarter or every six months, pull out that plan and ask, are you on track with saving or investment goals?
Did you change jobs or add a family member?
And don’t forget about your asset allocation. If it needs rebalancing, do it. But do it logically.
Emotion can be your worst enemy here. Keep emotions out of it. Instead, look at how your portfolio performed against benchmarks.
If it’s off, figure out why. Make logical adjustments based on what’s best for your long-term goals.
Remember, the market swings won’t change your success. Your plan will. Stick to your plan and adapt when necessary.
Trust me, this is the way to smarter financial decisions.
Your Move: Secure Your Wealth Today
Feeling stuck in financial uncertainty sucks, doesn’t it? I get it. But now, armed with a full financial plan, you’re ready to break free.
This isn’t just a vague promise. It’s a strategic blueprint. You’ve got the tools to build wealth, from cash flow analysis to strategic reviews.
And here’s the kicker: it works.
All that’s left? Take action. Start with Step 1, complete the cash flow analysis, and watch your financial control grow.
Don’t just sit there. Dive in and transform your future. Ready for the change?
Your financial future is calling. Answer it.
 Founder & CEO
There is a specific skill involved in explaining something clearly — one that is completely separate from actually knowing the subject. Jorveth Ollvain has both. They has spent years working with smart budgeting tools in a hands-on capacity, and an equal amount of time figuring out how to translate that experience into writing that people with different backgrounds can actually absorb and use.
Jorveth tends to approach complex subjects — Smart Budgeting Tools, Investment Portfolio Insights, Market Momentum being good examples — by starting with what the reader already knows, then building outward from there rather than dropping them in the deep end. It sounds like a small thing. In practice it makes a significant difference in whether someone finishes the article or abandons it halfway through. They is also good at knowing when to stop — a surprisingly underrated skill. Some writers bury useful information under so many caveats and qualifications that the point disappears. Jorveth knows where the point is and gets there without too many detours.
The practical effect of all this is that people who read Jorveth's work tend to come away actually capable of doing something with it. Not just vaguely informed — actually capable. For a writer working in smart budgeting tools, that is probably the best possible outcome, and it's the standard Jorveth holds they's own work to.